×
Home Current Archive Editorial board
Contact
Vol 20, No 40 (2026)

Volume 20 Issue 40 2026

Publishing collaboration

info

Edited by:

Vitomir Starčević

Vol. 20, No. 40 (2026):

Published: 11.09.2026.

Novi Ekonomist

Journal indexing and metrics

56 DAYS

Median submission to first decision

10 DAYS

Median acceptance to publication

Online First
See all
Scientific article Fiscal Economics Online First
Cross-Country Differences, Dynamics and Convergence of Transport Tax Revenue-to-GDP Ratios: Evidence from OECD Countries

By Giannis Adamos, Jadranka Đurović Todorović, Branimir Kalaš, Milica Ristic Cakic

Transport tax revenue-to-GDP ratios differ considerably across OECD countries, both in their levels and changes over time. This paper examines these differences, the dynamics of transport tax revenue as a share of GDP, and convergence between 2017 and 2024. The analysis covers 38 countries and uses a balanced panel of 304 country-year observations. The results show a general downward trend in transport tax revenue relative to GDP. Compared with 2017, the decline became statistically significant in 2019 and reached 0.104 percentage points of GDP by 2024. Countries with higher initial transport tax revenue-to-GDP ratios experienced larger absolute reductions, providing some evidence of convergence. However, this finding is not confirmed by the logarithmic specification or measures of cross-country dispersion. The results also show no significant change in the level or trend of transport tax revenue relative to GDP around 2020, as the decline had started earlier and continued afterwards. These findings demonstrate that declining transport tax revenue-to-GDP ratios and cross-country convergence represent distinct processes and highlight the persistence of substantial heterogeneity across OECD economies. From a policy perspective, the results underscore the importance of monitoring the fiscal evolution of transport taxation at a time when changes in mobility, vehicle technologies, and environmental policy are reshaping traditional transport-related tax bases.
Current issue
11.09.2026. Scientific article
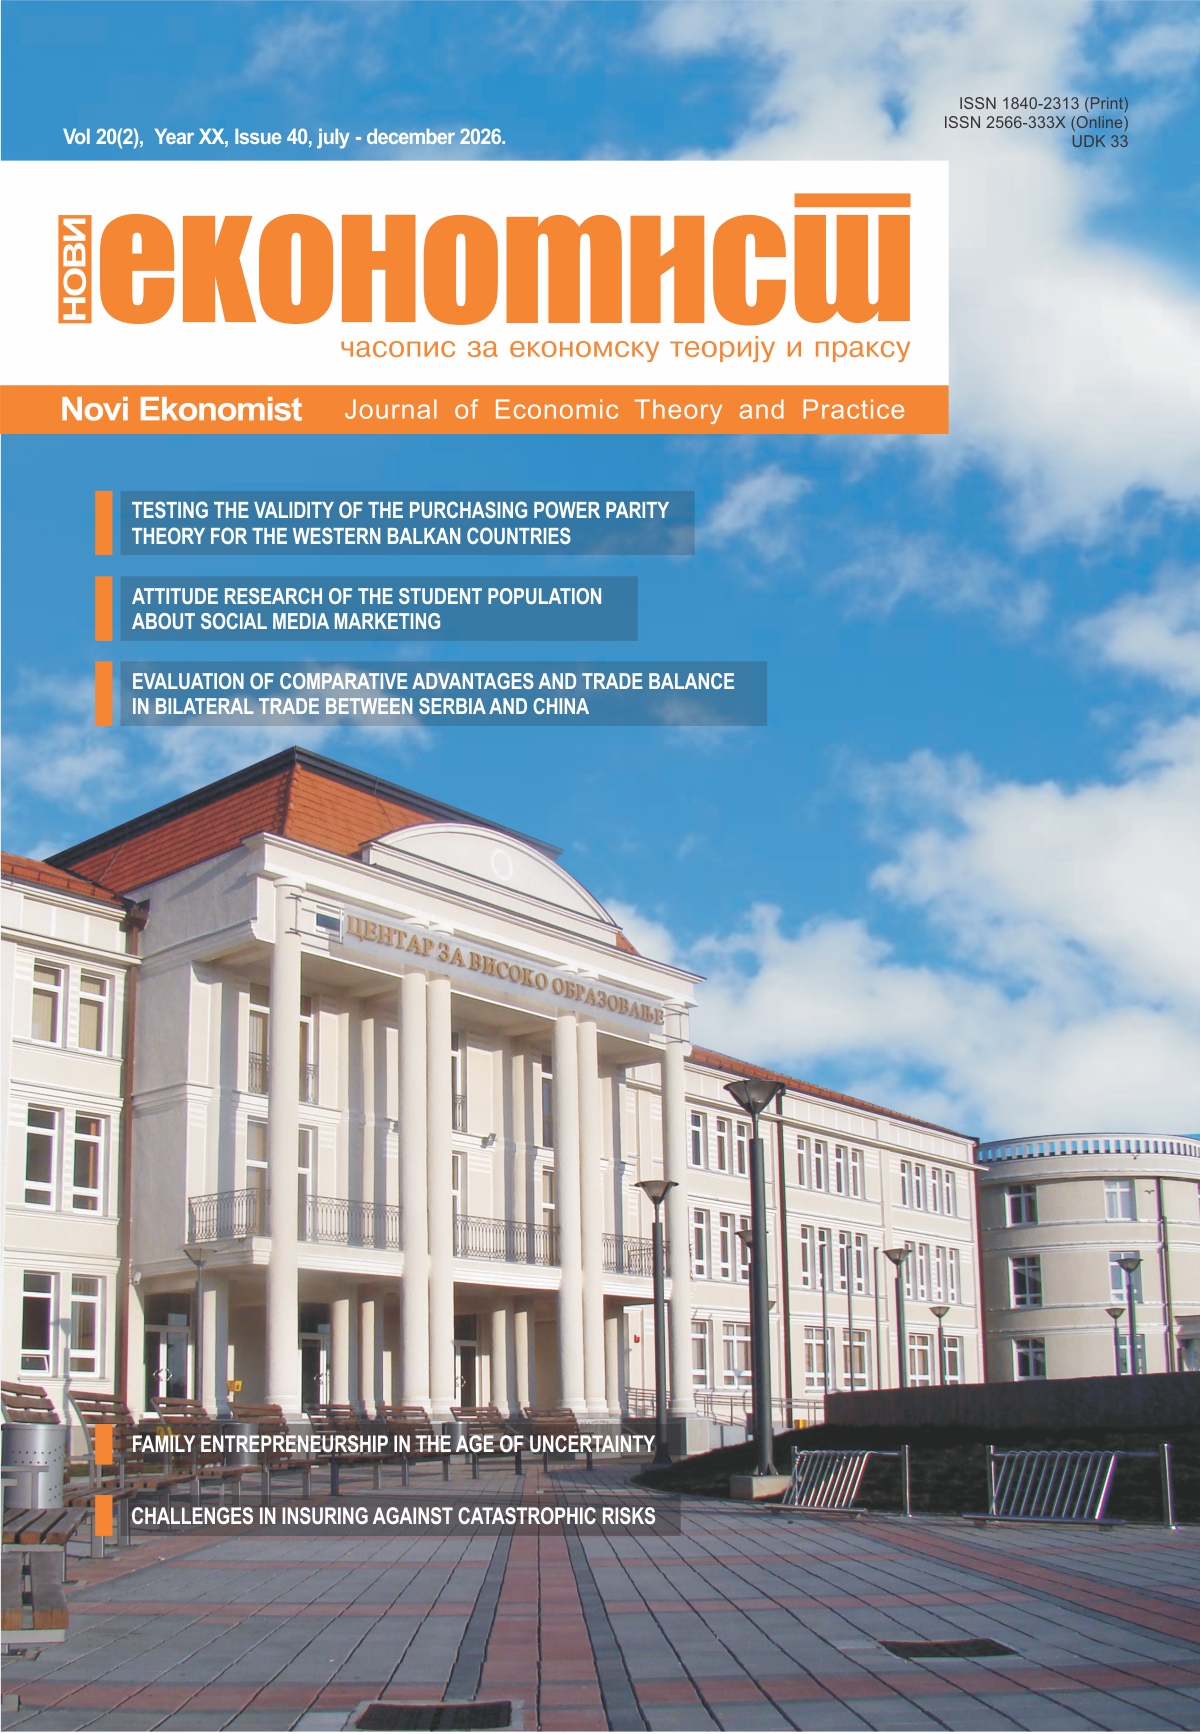
TESTIN`G THE VALIDITY OF THE PURCHASING POWER PARITY THEORY FOR THE WESTERN BALKAN COUNTRIES

By Srđan Kujundžić, Luka Marković

11.09.2026. Scientific article
ATTITUDE RESEARCH OF THE STUDENT POPULATION ABOUT SOCIAL MEDIA MARKETING

By Dejan Tešić, Neda Tešić

11.09.2026. Scientific article
EVALUATION OF COMPARATIVE ADVANTAGES AND TRADE BALANCE IN BILATERAL TRADE BETWEEN SERBIA AND CHINA

By Vesna Petrović, Zlatko Simikić

11.09.2026. Review
FAMILY ENTREPRENEURSHIP IN THE AGE OF UNCERTAINTY

By Sergei Polbitsyn, Biljana Kovačević, Michael Olumekor, Katarina Božić

11.09.2026. Review
CHALLENGES IN INSURING AGAINST CATASTROPHIC RISKS

By Jelena Kočović, Nataša Tešić, Marija Koprivica

Recent issues
See all
Most read
See all
Scientific article
C EFFICIENCY RATIO AS A MEASURE OF VAT EFFICIENCY IN EU DEVELOPING COUNTRIES AND SERBIA

By Jadranka Đurović-Todorović, Milica Ristić, Marina Đorđević

The policy led by a large number of developing countries, with the aim of increasing indirect taxes, has opened the issue of Value Added Tax (VAT) efficiency. Reforms of tax systems of developing countries generally involve an increase in standard rates in order to increase VAT, which is the main source of public revenues. In such a way, developing countries determine the VAT efficiency and the amount of revenue that could be collected by indirect taxation. The article sums up works of different scientists, dealing with the impact of determinants on VAT efficiency. The subject of this paper is an analysis of the factors that influence the C efficiency ratio. The main objective of the paper is to analize the impact of the change in the standard rate on the ratio. Theoretical analyses of standard rates and other factors that have reflections on the VAT collection efficiency explicitly prove that there are different ways to improve the efficiency of VAT collection, and exclude an increase in the standard rate. An increase in the standard rate provides a balance of negative effects, which can be blurred by recorded tax revenues. We focused on the countries of the European Union: Bulgaria, Czech Republic, Estonia, Greece, Croatia, Latvia, Hungary, Poland, Romania, Slovakia, Slovenia, Lithuania during the 2000-2016 period. These countries experienced significant changes in government during economic transformation, and where VAT is the main source of public revenues. The last section analize an increse in VAT rate and C efficiency ratio in Serbia and conteins conclusions. The paper indicates the imperfection of inadequately defined VAT rates on economic growth and development in analized countries. Based on analyses we can conclude that the increase in the standard rate have negative reflections on the VAT efficiency, and that it was one of the factors of the continuous decline in C-efficiency.

Review
THE CONCEPT OF CLOUD MARKETING

By Mirjana Maksimović, Zvjezdana Gavrilović

28.06.2024. Scientific article
FISCAL RULES AT THE LOCAL LEVEL ARE A CONDITION FOR STABLE PUBLIC FINANCES IN THE REPUBLIC OF SRPSKA

By Biljana Srdić Gojković

The fiscal position of municipalities and cities has a great influence on the overall fiscal position of the Republic of Srpska. Bearing in mind that according to the Law on the Budget System, the budget system of the Republika Srpska consists of the budget of the Republic, the budget of municipalities and cities and the financial plans of the funds, then it is clear that the realization of the budget of municipalities and cities with a high budget deficit represents a great risk for excessive realization of the deficit at the level of the Republic . Republika Srpska does not have defined fiscal rules for local self-government units. However, bearing in mind that according to the Law on Fiscal Responsibility in the Republic of Srpska, the consolidated budget deficit is determined as the sum of consolidated budget deficits, the budget of the Republic, the budget of municipalities and cities, and the budget of funds, it is clear that the realization of an excessive deficit of municipalities and cities affects the fiscal rule on deficit at the level of Republika Srpska. The results of the analysis in this paper indicate the need to introduce fiscal rules for local self-government units. The fiscal stability of local self-government units has a positive effect on the overall fiscal stability of the Republic, especially if mechanisms are introduced to suppress the excessive deficit of local self-government units.

ABSTRACTING AND INDEXING

The Novi Ekonomist is included to all relevant abstract and citation databases. For a full list visit About page. These include (but are not limited to):

Indexing